
Citi Islamic Investment Bank E.C.
Citi Islamic Investment Bank (CIIB) was incorporated in Bahrain in 1996 as a fully owned subsidiary of Citicorp Banking Corporation. CIIB is licensed by the Central Bank of Bahrain as an Islamic Wholesale Bank and was the first Islamic Bank established by a major international financial Institution. Citi has been active in the Islamic finance industry since 1981, when it opened its first Islamic “window” in London. Citi Islamic has been able to leverage Citi’s global network and products to seamlessly provide innovative Islamic banking products and solutions for almost four decades.
Citi Islamic has successfully arranged several billion dollars of Islamic transactions for issuers in the Middle East, Asia, Europe and Latin America. This includes the origination, structuring and distribution of numerous landmark Sukuk, syndications, project financings, Islamic advisory and investment products. Today, the bank is ranked as the leading bookrunner of international Islamic Finance transactions.
Our integrated approach is designed to meet the Islamic banking needs of our corporate, public sector, financial institutions and high net worth clients. Through our network, we are able to provide world class financing, investment, liquidity management, advisory and risk management solutions.
What You Can Expect From Us & What We Expect From Ourselves
Citi Islamic Investment Bank’s mission is to serve as a trusted partner to our clients by responsibly providing Islamic financial services that enable growth and economic progress. We are Citi, the global bank – an institution connecting millions of people across hundreds of countries and cities. We have 200 years of experience helping our clients meet the world's toughest challenges and embrace its greatest opportunities.
We work with companies to optimize their daily operations, whether they need working capital, to make payroll or export their goods overseas. We provide financing support to governments at all levels, so they can build sustainable infrastructure, such as housing, transportation, schools and other vital public works.
These capabilities create an obligation to act responsibly, do everything possible to create the best outcomes, and prudently manage risk. We strive to earn and maintain the public's trust by constantly adhering to the highest ethical standards in both the traditional and Islamic finance world. We ask our colleagues to ensure that their decisions pass three tests: they are in our clients' interests, create economic value, and are always systemically responsible. When we do these things well, we make a positive financial and social impact in the communities we serve and show what a global bank can do.
Citi Islamic’s Sharia Supervisory Board (SSB) is comprised of internationally renowned and respected scholars, all of whom are on the Sharia boards of various other regional and international institutions, ensuring widespread acceptance among Islamic investors.
The SSB is responsible for providing external Sharia oversight and direction to the Islamic banking activities of Citi, including review and approval of proposed Islamic products and services.
The Board also conducts regular Sharia audits to ensure Citi’s offerings are in compliance with Islamic principles.
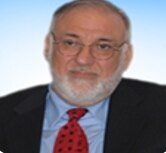
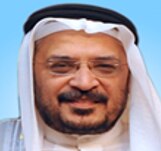
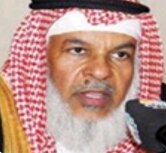
Dr. Nazih Hammad | Sheikh Nizam Yaquby | Dr. Mohammed Ali Elgari |
|
|
|
| Dr. Nazih Hammad is a graduate of the Faculty of Sharia at the University of Damascus, Syria and holds a Ph. D. in Islamic Jurisprudence from Cairo University. Holds a Ph.D. in Islamic Jurisprudence from Cairo University. Is the author of several research papers and books on Islamic jurisprudence, banking, and finance. Also serves on the boards of: Ratings Intelligence. Standard and Poor’s. Selected Institutions: Fiqh Council of North America, Islamic International Rating Agency, Ratings Intelligence, Standard and Poor's. | Sheikh Nizam Yaquby studied traditional Islamic studies under the guidance of eminent Islamic scholars from different parts of the world. He has a BA in economics and comparative religions from McGill University, Canada. He has served in Bahrain Mosques from 1981-1990 where he taught Tafsir, Hadith and Fiqh in Bahrain since 1976. He has published several articles and books on various Islamic subjects including banking and finance. Selected Institutions: AAOIFI, BNP Paribas, Calyon, HSBC, Credit Suisse. | Dr. Mohammed Ali Elgari holds a PhD from the University of California. He is a Professor of Islamic Economics at King Abdulaziz University, Jeddah, Saudi Arabia and former director of the Centre for Research in Islamic Economics, in the same university. He authored several books in Islamic finance and published tens of articles on the subject both in Arabic and English. Dr. Elgari is the recipient of the Islamic Development Bank prize in Islamic Banking and Finance for the year 1424H (2004). Selected Institutions: AAOIFI, BNP Paribas, AIG Takaful, Calyon, HSBC. |
Please click on the below links to view the Financial Reports
2025
3rd Quarter Composition of Capital Disclosures
3rd Quarter Financial Statements (English)
3rd Quarter Financial Statements (Arabic)
3rd Quarter LCR, NSFR, and Leverage Ratios
2nd Quarter Pillar III Disclosure
2nd Quarter Composition of Capital Disclosures
2nd Quarter Financial Statements (English)
2nd Quarter Financial Statements (Arabic)
2nd Quarter LCR, NSFR and Leverage Ratios
1st Quarter Composition of Capital Disclosures
1st Quarter Financial Statements (English)
1st Quarter Financial Statements (Arabic)
1st Quarter LCR, NSFR and Leverage Ratios
2024
4th Quarter Composition of Capital Disclosures
4th Quarter Financial Statements (English)
4th Quarter Financial Statements (Arabic)
4th Quarter LCR, NSFR and Leverage Ratios
3rd Quarter Composition of Capital Disclosures
3rd Quarter Financial Statements (English)
3rd Quarter Financial Statements (Arabic)
3rd Quarter LCR, NSFR and Leverage Ratios
2nd Quarter Pillar III Disclosure
2nd Quarter Composition of Capital Disclosures
2nd Quarter Financial Statements (English)
2nd Quarter Financial Statements (Arabic)
2nd Quarter LCR, NSFR and Leverage Ratios
1st Quarter Composition of Capital Disclosures
1st Quarter Financial Statements (English)
1st Quarter Financial Statements (Arabic)
1st Quarter LCR, NSFR and Leverage Ratios
2023
4th Quarter Composition of Capital Disclosures
4th Quarter Financial Statements (English)
4th Quarter Financial Statements (Arabic)
4th Quarter LCR, NSFR and Leverage Ratios
3rd Quarter Composition of Capital Disclosures
3rd Quarter Financial Statements (English)
3rd Quarter Financial Statements (Arabic)
3rd Quarter LCR, NSFR and Leverage Ratios
2nd Quarter Pillar III Disclosure
2nd Quarter Composition of Capital Disclosures
2nd Quarter Financial Statements (English)
2nd Quarter Financial Statements (Arabic)
2nd Quarter LCR, NSFR and Leverage Ratios
1st Quarter Composition of Capital Disclosures
1st Quarter Financial Statements (English)
1st Quarter Financial Statements (Arabic)
1st Quarter LCR, NSFR and Leverage Ratios
2022
4th Quarter Composition of Capital Disclosures
4th Quarter Financial Statements (English)
4th Quarter Financial Statements (Arabic)
4th Quarter LCR, Leverage and NSFR Ratios
3rd Quarter Composition of Capital Disclosures
3rd Quarter Financial Statements (English)
3rd Quarter Financial Statements (Arabic)
3rd Quarter LCR, NSFR and Leverage Ratios
2nd Quarter Pillar III Disclosure
2nd Quarter Composition of Capital Disclosures
2nd Quarter Financial Statements (English)
2nd Quarter Financial Statements (Arabic)
2nd Quarter LCR, NSFR and Leverage Ratios
1st Quarter Composition of Capital Disclosures
1st Quarter Financial Statements (English)
1st Quarter Financial Statements (Arabic)
1st Quarter LCR, NSFR and Leverage Ratios
2021
4th Quarter Composition of Capital Disclosures
4th Quarter Financial Statements (English)
4th Quarter Financial Statements (Arabic)
4th Quarter LCR, NSFR and Leverage Ratios
3rd Quarter Composition of Capital Disclosures
3rd Quarter Financial Statements (English)
3rd Quarter Financial Statements (Arabic)
3rd Quarter LCR, NSFR and Leverage Ratios
2nd Quarter Pillar III Disclosure
2nd Quarter Composition of Capital Disclosures
2nd Quarter Financial Statements (English)
2nd Quarter Financial Statements (Arabic)
2nd Quarter LCR, NSFR and Leverage Ratios
1st Quarter Composition of Capital Disclosures
1st Quarter Financial Statements (English)
1st Quarter Financial Statements (Arabic)
1st Quarter LCR, NSFR and Leverage Ratios
2020
4th Quarter Composition of Capital Disclosures
4th Quarter Financial Statements (English)
4th Quarter Financial Statements (Arabic)
4th Quarter LCR, NSFR and Leverage Ratios
3rd Quarter Composition of Capital Disclosures
3rd Quarter Financial Statements (English)
3rd Quarter Financial Statements (Arabic)
3rd Quarter LCR, NSFR and Leverage Ratios
2nd Quarter Pillar III Disclosure
2nd Quarter Composition of Capital Disclosures
2nd Quarter LCR, Leverage and NSFR Ratios
View the Letter for Customer Feedback.
Citi is one of the leading players in Sukuk and syndicated Islamic financings. Citi's Capital Markets Origination business is focused on the capital-raising needs of institutional clients, from inaugural issuances and exchanges to cross-border transactions and first-of-their-kind landmark structures. Citi’s Agency & Trust team has industry leading experience with documenting and executing deals worldwide, including arranging for Sukuk transactions through Sharia compliant escrow arrangements, among other Issuer Services.
Citi’s experience in the Sukuk market includes repeat issuances from across regions and sectors, including financial institutions, corporates and sovereigns from the MENA region. Citi remains the first-choice book runner in the MENA region, as both corporate and sovereign clients continue to trust us with arranging their successful Eurobond offerings. We are proud of our legacy of leadership and excellence and are committed to continue to serve our clients in helping them to achieve their financing needs.
Over the last 3 years alone, Citi has advised multiple Sovereigns, Quasi-Sovereigns, Corporates and Financial Institutions on Sukuk globally, in the volume of around US$ 35 billion. Citi has worked closely with many issuers in developing innovative Sukuk structures which have become market benchmarks.
Citi Islamic has been at the heart of multiple first-of-their kind landmark structures:
Republic of Indonesia – USD3 bn Trust Certificates due 2023 and 2028
On February 22, 2018, the Republic of Indonesia successfully priced an international Sukuk offering totaling USD 3 bn, including its debut offering in green format. Citi served as Joint Book runner, Billing and Delivery Bank on this landmark transaction.
- First-ever green Sukuk offering by any sovereign globally.
- First USD sovereign green offering, in either Sukuk or conventional formats.
- Accessed a window of relative stability without any competing supply for aggregate size of USD 3 bn, which remains to be the largest Sukuk offering by a non-GCC issuer to-date.
- Maximized green structure and full investment grade ratings to set all-time low spreads to U.S. Treasury for any Sukuk offering by the Republic of Indonesia.
- Set the flattest curve between any 5- and 10-year Sukuk offering by the Republic.
2.4x oversubscribed across both tranches, featuring sponsorship from investors of the highest. - quality, green focused funds and sovereign-related entities inclusive.
Emirates ECGD – USD 913 mn Guaranteed Sukuk Certificates
On March 25, 2015, Citigroup acted as Joint Structuring Agent and Joint Lead Manager on the inaugural USD 913,026,000 Sukuk Certificates offering for Emirates, guaranteed by Her Britannic Majesty’s Secretary of State Acting by the Exports Credits Guarantee Department of the UK Government (“ECGD”)
The Trust Certificates Due March, 2025 represent the largest single capital markets financing of A380-800 aircraft. The Sukuk structure has been approved by the Sharia Supervisory Board of Citi Islamic Investment Bank, and carries endorsements from each of the Joint Lead Managers’ Sharia boards where applicable. The Sukuk utilized the Sharia concepts of Istisna and Ijara. To facilitate an aircraft prefunding transaction, the Sukuk utilized the concept of Rights to Travel (ATKMs) to create tangibility for trading purposes, and an Ijara on a forward lease basis prior to acquisition of the Aircraft.
The Kingdom of Saudi Arabia – USD 9 bn 144a / RegS Sukuk
On 12th April 2017, the Kingdom of Saudi Arabia priced a multi tranche USD 9 billion debut Sukuk offering, split evenly across 5 and 10 year tranches and a final order book in excess of USD 35 billion. Citi was a joint Global Coordinator on this transaction. The transaction followed the Kingdom’s record breaking USD 17.5 billion triple-tranche debut bond offering in October 2016, on which Citi was also Joint Global Coordinator.
Largest Ever Sukuk Offering, by a Factor of 2.25x.
Largest Ever order book for a Two-tranche Offering.
Largest Sukuk order book ever, with highest Islamic investor demand.
Citi Islamic’s Services business provides integrated Sharia-compliant cash management and trade finance services to multinational corporations, financial institutions and public sector organizations around the globe in both local and foreign currencies, complete with Citi’s established electronic banking platform – CitiDirect® and customer service – CitiService®.
Islamic Current Accounts
Citi’s Islamic Current Accounts provides clients with Sharia-compliant, non-profit bearing accounts for corporates. Our customers could use their accounts to process payments and carry out day to day banking activities.
Under the sharia principles, Citi accepts funds from the depositor for an unspecified period with a promise to return the funds on demand. The bank may utilize the balances in this account in Sharia-compliant investment activities only.
Distinctive features of our Islamic Current Accounts:
- Sharia-compliant.
- Local & Foreign Currency.
- Cheque Book.
- Electronic Banking – CitiDirect®.
- Payments & Collections – Local & Cross Border.
- Customer Service – CitiService®.
- Book Profit Earning Islamic Term Investments.
- Transfers to Profit Earning Savings Account.
Under our Services Business, Citi Islamic provides integrated Sharia-compliant cash management and trade finance services to multinational corporations, financial institutions and public sector organizations around the globe in multiple currencies, complete with Citi’s established electronic banking platform – CitiDirect® and customer service – CitiService®.
Murabaha Placement
Under the Islamic principle of Murabaha, Citi is able to enter into a Sharia-compliant commodity trade with clients. As the agent, Citi purchases permissible commodities for the client which is then sold on a deferred payment basis at a higher price, allowing the client to earn profit.
Islamic Trade Financing
The Islamic Trade Financing provides short-term Sharia-compliant refinancing for payment obligations under Documentary Letters of Credit, Open Accounts, and Documentary Collections. Islamic Trade Financing is provided to Islamic Financial Institutions under a Murabaha agreement to finance the underlying trade flows of their clients.
Murabaha Liquidity Product (Islamic Nostro)
Citi’s Murabaha Liquidity Product provides clients with Sharia-compliant returns on surplus liquidity in USD and other major currencies. The Client agrees to place balances in a non-interest bearing account in consideration of receiving returns under a Murabaha agreement. This solution offers full access to liquidity in the account and clients are able to withdraw amounts from their accounts.
Complaints Procedure
Please note that the below mentioned complaint handling process is applicable only to complaints or queries raised by customers of Citibank, N.A., Bahrain Branch ("Citi Bahrain") regarding Citi Bahrain products, services or offers. Citi Bahrain shall not be responsible for handling any complaints or queries raised by customers of Citibank N.A. branches outside of Bahrain or any other Citigroup entities.
At Citi, we endeavor to provide a world-class level of service through a continuous process of staff training and improvement in our processes. Whilst we are grateful for your positive feedback with regards to our standards of service, it is equally important for us to welcome any concerns you may have with regards to the service provided by our bank. This will help us in further improving our existing standards.
In this regard, you may register any concerns or suggestions regarding the Service through the following channels.
Direct number: +973 17588555 / +973 17584109 / 17584207
Fax number: +97317588545
Email: citiservice.bahrain@citi.com
Specifically, for complaints, please reach out to our Complaints Officer Ms. Lamees Almahroos at lamees.abbas.almahroos@citi.com or telephone +973 17584123.
We aim to acknowledge your complaint within five working days and will contact through the contact details provided. A comprehensive investigation into the concern or complaint will then be raised. You can find the full complaints guide here.
Citi's Markets business provides world-class financial products and services as diverse as the needs of the thousands of corporations, institutions, governments and investors that Citi serves. Citi Islamic has developed a comprehensive range of innovative investment, financing, and risk management solutions for clients seeking to comply with the principles of Sharia, whilst preserving the economics associated with conventional financial transactions.
Investment Solutions
Citi’s Oasis Certificate Programme has the ability to offer clients a packaged Sharia-compliant security which mirrors the economics of a variety of conventional notes and warrants. The asset mix which Oasis holds gives exposures to several benchmark asset classes, including Equities, Commodities, FX, Rates, and Alternatives. All assets are in compliance with Sharia, as are all additional agreements that Oasis enters into.
Distinctive features of our Oasis Certificate Programme:
Independent Oversight: all of the products are subject to the oversight and approval of Citi’s Sharia Supervisory Board.
Operation ease: Instruments are issued as securities. This means that clients may simply purchase the security in a similar fashion to equities and Sukuk, without the need for bilateral documentation.
Breadth of Product Offering: Investment products may be linked to a wide variety of asset classes and issued in principal protected or non-principal protected formats.
Collateralized Murabaha(Islamic Repo)
Citi offers clients with Multicurrency Murabaha financing collateralized by liquid and readily marketable Sharia-compliant securities, such as Sukuk under a deferred payment basis. Financing tenors can be upto 5 years. Citi’s Master Collateralized Murabaha Agreement is based on the International Islamic Finance Market’s Master Collateralized Murabaha Agreement and the collateral can be pledged or transferred depending on the client’s preference.
Risk Management Solutions
Citi has developed Sharia-compliant hedging solutions for corporates akin to traditional swap agreements, cross currency, and other derivatives.
Citi’s Profit Rate Swap and the Currency Profit Rate Swap achieves Sharia-compliance by using reciprocal Murabaha transactions whereby a series of transactional steps are undertaken by both parties to generate a fixed and floating profit rate payable on each leg of the swap. This allows clients to achieve the immunization benefits of traditional derivatives and execute efficient Asset/Liability management, while maintaining Sharia compliance.
Citi uses the ISDA/IIFM Tahawwut Master Agreement.
Managing Risk – An Overview
For Citi Bahrain, effective risk management is of primary importance to its overall operations. Accordingly, Citi’s risk management process has been designed to monitor, evaluate and manage the principal risks it assumes in conducting its activities. Specifically, the activities that Citi engages in, and the risks those activities generate, must be consistent with Citi’s mission and value proposition, the key principles that guide it, and Citi’s risk appetite.
Under Citi’s mission and value proposition, which was developed by Citi’s senior leadership and distributed throughout the Company, Citi strives to serve its clients as a trusted partner by responsibly providing financial services that enable growth and economic progress while earning and maintaining the public’s trust by constantly adhering to the highest ethical standards. As such, Citi asks all employees to ensure that their decisions pass three tests: (1) they are in our clients’ interests (2) create economic value and (3) they are always systemically responsible. Additionally, Citi evaluates employees’ performance against behavioral expectations set out in Citi’s leadership standards, which were designed in part to effectuate Citi’s mission and value proposition. Other culture-related efforts in connection with conduct risk, ethics and leadership, escalation and treating customers fairly help Citi to execute its mission and value proposition.
Citi’s risk governance framework consists of the policies, standards, procedures and processes through which Citi identifies, assesses, measures, manages, monitors, reports and controls risks across the Company.
It also emphasizes Citi’s risk culture and lays out standards, procedures and programs that are designed and undertaken to enhance the Company’s risk culture, embed this culture deeply within the organization, and give employees tools to make sound and ethical risk decisions and to escalate issues appropriately.
Citi manages its risks through each of its three lines of defense: (i) business management, (ii) independent control functions and (iii) internal audit. The three lines of defense collaborate with each other in structured forums and processes to bring various perspectives together and to lead the organization toward outcomes that are in clients’ interests, create economic value and are systemically responsible.
Managing Operational Risk – An Overview
Operational risk for Citi Branch, is managed in line with the Operational Risk Management Policy (issued at a group level), which defines an overall framework designed to balance strong corporate oversight with well-defined independent risk management. Citi Bahrain has also adopted the ‘Three Lines of Defense’ Governance Structure for effective management of Operational Risk as well as the “Manager’s Control Assessment (MCA)” Standards and Procedure to assist / support business managers to self-assess significant operational risks and key controls and identify and address weaknesses in the design and / or operating effectiveness of internal controls that mitigate significant operational risks.
Citi Bahrain also has a clear process for identifying, accounting and reporting events related to operational risk. Each loss (or gain) posted on the books of the Bank, & recording the same in a database (Loss Capture system) in line with the thresholds as defined by Citi’s Operational Risk Management Data Quality Standards. An analysis of the significant losses reported are done in order to take the necessary corrective actions & implement mitigating controls.
Additionally, the in-country Operational Risk Management, works proactively with the businesses and other independent control functions to embed a strong operational risk management culture and framework across Citi. Operational Risk Management engages with the businesses to ensure effective implementation of the Operational Risk Management framework by focusing on (i) identification, analysis and assessment of operational risks, (ii) effective challenge of key control issues and operational risks and (iii) anticipation and mitigation of operational risk events.
At a country level there exists a Country Coordinating Committee (CCC) which is the principal committee for escalation and reporting of operational risk events, internal control, legal, compliance, regulatory and risk issues. The key objectives of the CCC are:
To discuss and challenge the management of the most significant risk and control issues impacting the local business activities, including the proposed associated action and remediation plans.
To monitor the management of business risks that affect the franchise and as well as its constituent parts through assisting Senior Management to focus on the most significant risk, control issues, emerging risks impacting business objectives and activities, and the timeliness and effectiveness of corrective actions.
The Citi Country Officer (CCO) of Citi Bahrain, serves as the Committee chair and the committee comprises of key representatives from the First, Second & Third Lines of Defense.
Operational Risk Appetite Statement
Objectives
Citi Bahrain’s goal is to keep operational risk at appropriate levels relative to the characteristics of its businesses, the markets in which it operates, its capital and liquidity, and the competitive, economic and regulatory environment. The entity recognizes that operational risk is inherent in its global business activities and related support processes. To anticipate, mitigate and control operational risk, the entity follows Citi-wide policies, and the institutional framework for assessing, monitoring and communicating operational risks and the overall operating effectiveness of the internal control environment across Citi.
Risk Appetite
Citi Bahrain also recognizes that operational risk can occur broadly and has impact beyond financial losses. Local Management has implemented a Manager’s Control Assessment (MCA) program that relies on key indicators across various operational risk categories and established methodologies and tools to facilitate monitoring where appropriate so that any exceptions and / or negative trends are captured in operational risk management reporting. Citi Bahrain:
- Maintains a well-controlled operating environment for its businesses and functions to mitigate the most material risks (e.g., including but not limited to external fraud and errors in processing, data);
- Expects employees to uphold the highest ethical standards of conduct in accordance with Citi’s values, policies and control framework and report concerns as set forth in the employee code of conduct;
- Expects Third Parties providing significant products or services to businesses and support areas will hold themselves to the highest standards of conduct in accordance with Citi’s values, policies and control framework;
- Does not tolerate:
- Violations of laws or regulations,
- Fraud committed by its staff,
- Deliberate actions that result in harm to clients;
- The entity recognizes that mistakes occur but has very little appetite for:
- Activities which could result in financial statements that inadequately reflect Citi’s financial profile or in a material weakness in financial reporting controls,
- Threats to company assets or data arising from malicious attacks or inadequate protection,
- Damage from inability to timely recover from a major interruption to business operations, technology or facilities,
- Behavior inconsistent with responsibly providing financial services or which could result in reputational harm.
Citi Islamic Investment Bank is licensed by the Central Bank of Bahrain as an Islamic Wholesale bank.
Citi Islamic Investment Bank E.C., is wholly owned subsidiary of Citigroup Inc., registered in the Kingdom of Bahrain as an Islamic wholesale bank